
AED 1 Trillion to Lend: How GCC Companies Become Eligible for Sustainable Finance

UAE banks have committed to mobilise more than AED 1 trillion in sustainable finance by 2030. First Abu Dhabi Bank (FAB) alone is aiming for over AED 500 billion. The money is there. The question for a Gulf CFO is whether the company can qualify for it, and that comes down to evidence, not intent.
GCC sustainable finance eligibility for companies is set less by the size of the UAE banks’ AED 1 trillion pledge and more by what a borrower can prove: where the money goes, which targets it will hit, and whether the numbers hold up when an outside reviewer checks them.
Spectreco, a US-headquartered sustainability technology and advisory company with offices in Atlanta, Dubai, Riyadh, Muscat and Lahore, works with GCC corporates, developers and banks on that evidence. This article is part of our ESG readiness pillar.
On this page
- What is the UAE AED 1 trillion sustainable finance pledge?
- Is GCC sustainable finance growing or slowing in 2026?
- What do banks check before approving a green or sustainability-linked loan?
- Does green finance lower your interest rate?
- How to become eligible for sustainable finance in five steps
- Frequently asked questions
What Is the UAE AED 1 Trillion Sustainable Finance Pledge?
Direct answer: The UAE Banks Federation announced the pledge on 4 December 2023, at a Central Bank of the UAE (CBUAE) event during COP28. UAE banks committed to mobilise over AED 1 trillion in sustainable finance by 2030. It is a collective industry target. It is not a fund a company can apply to directly.
Each bank meets its share through its own green loans, sukuk and bonds, so eligibility is decided bank by bank, deal by deal.
Source: CBUAE, 4 Dec 2023
The other GCC finance pools
- FAB: over AED 500 billion (USD 135 billion) in sustainable and transition financing by 2030, announced on 5 December 2023. FAB had facilitated more than AED 100 billion by the end of September 2023.
- QNB Group: more than QR41 billion of sustainable financing in 2025, plus a EUR 750 million green bond, the largest by a bank in the Middle East at the time of issuance.
- Sustainable sukuk: Middle East issuance reached a record USD 11.4 billion in 2025, up from USD 7.9 billion in 2024, according to S&P Global Ratings.
Sources: FAB, 5 Dec 2023, The Peninsula, 25 Mar 2026, S&P Global Ratings via Arab News, 17 Feb 2026
S&P also expects Middle East sustainable bond issuance of USD 20 billion to USD 25 billion in 2026, after regional volumes rose about 3% in 2025 while global issuance fell 21%. Our guide to green sukuk and ESG disclosure in the GCC covers the issuer side.
Source: S&P Global Ratings via Arab News, 17 Feb 2026
Is GCC Sustainable Finance Growing or Slowing in 2026?
Direct answer: Both. The pledges stand, but issuance has slowed. Fitch Ratings put GCC ESG debt issuance at about USD 8 billion in the first nine months of 2026. That is down 44% year on year. Fitch linked the fall to weaker debt capital market activity during the Iran conflict.
The region still leads: the GCC made up about 39% of emerging-market US dollar ESG issuance excluding China, the largest share. The 44% fall covers all currencies; the 39% share covers dollar deals only.
Loans are softer too. The Loan Market Association (LMA) reports EMEA sustainable loan volumes of USD 62.35 billion in Q1 2026, down about 20% from USD 77.48 billion a year earlier.
Sources: Fitch Ratings via TradeArabia, 20 Oct 2026, LMA Horizons, Q2 2026
What the slowdown means for borrowers
Spectreco’s read: a thinner market makes lenders more selective, not less. When fewer deals close, the ones that do tend to carry clean use-of-proceeds data and targets a reviewer can check. The pools are still large, but the queue now favours prepared borrowers.
What Do Banks Check Before Approving a Green or Sustainability-Linked Loan?
Direct answer: Lenders test two different things. For a green loan, they check that the money funds eligible green projects and is tracked and reported. For a sustainability-linked loan, they check that the targets are material and ambitious. They also require an outside reviewer to confirm the results every year.
The market standard for both is set by the LMA, whose loan principles were updated on 26 March 2025.
Green loans: use of proceeds
The Green Loan Principles (GLP) have four core components:
- Use of proceeds: the loan funds eligible green projects, described in the loan documents.
- Project evaluation and selection: the borrower explains how it chooses projects and which environmental goals they serve.
- Management of proceeds: the money is tracked so it can be traced to those projects.
- Reporting: an annual update listing the green projects, the amounts allocated, and their expected and achieved impact.
The GLP recommend quantitative impact measures where feasible, with the method behind them disclosed. External review is recommended where the borrower cannot show the expertise in-house.
Source: LMA Green Loan Principles, 26 Mar 2025
Sustainability-linked loans: KPIs and targets
The Sustainability-Linked Loan Principles (SLLP) have five components: selection of key performance indicators (KPIs), calibration of sustainability performance targets (SPTs), loan characteristics, reporting and verification. In practice, lenders look for:
- Material KPIs: tied to the borrower’s core business and measurable against a clear baseline.
- Ambitious targets: SPTs that go beyond business as usual and beyond what regulation already requires.
- Annual reporting: KPI data and a statement on target performance sent to lenders at least once a year.
- External verification: independent review of performance against each target is mandatory, carried out by a qualified external reviewer.
Early deals often fell short. A Harvard Business School study of 573 sustainability-linked loans found about half had no KPI linked to the SASB materiality map. Plan for the 2025 bar, not the early one.
Sources: LMA Sustainability-Linked Loan Principles, 26 Mar 2025, Loumioti and Serafeim, Harvard Business School, Nov 2022
Data quality: the test behind both
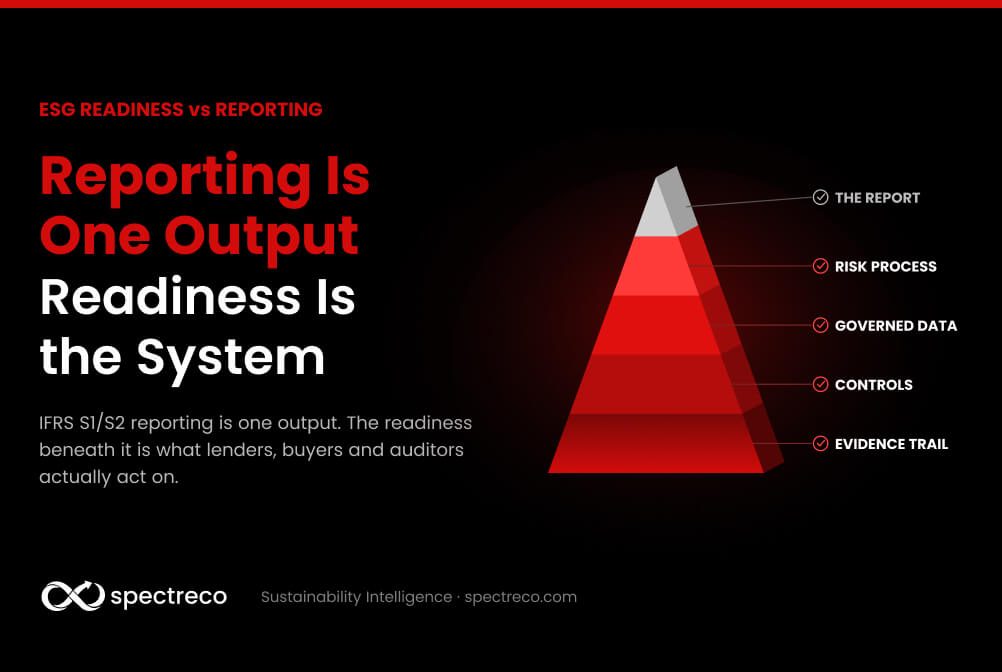
Both sets of principles assume the borrower already has governed data: a baseline, named owners, a method that stays the same each year, and records an outside reviewer can follow. In the UAE the national green taxonomy is still in design, so borrowers should build activity-level data now rather than wait for the final rules.
Does Green Finance Lower Your Interest Rate?
Direct answer: Sometimes, by a few basis points. The main prize is access to the money, not a discount. Published studies put the loan price effect at roughly 5 to 20 basis points. The green bond premium has largely disappeared since 2020.
- About 4.8 bps: the average margin adjustment across 573 sustainability-linked loans issued from 2017 to 2021 (Harvard Business School, November 2022).
- About 20 bps: the extra amount euro-area firms with no emission-reduction commitment paid on bank loans (Altavilla et al., CEPR, 2023).
- About 8 bps: the lower yield spread on green corporate bonds against conventional bonds (Federal Reserve, June 2022).
- Close to zero: where that green bond premium stood by 2020 (CBS Nordic ESG Lab, July 2025).
Sources: Loumioti and Serafeim, Harvard Business School, Nov 2022, Altavilla et al., CEPR, 2023, Caramichael and Rapp, Federal Reserve, Jun 2022, CBS Nordic ESG Lab, 18 Jul 2025
We found no public GCC loan that discloses its margin step, so treat these as international benchmarks. Plan for eligibility first and a small margin step second. See our guide to linking decarbonisation plans to the cost of capital.
How to Become Eligible for Sustainable Finance in Five Steps
- Pick the right instrument. Choose a green loan or green sukuk if you have identifiable green projects, such as a solar retrofit or a certified building. Choose a sustainability-linked loan if the improvement is company-wide.
- Build a baseline. Measure Scope 1 emissions (direct, from sources you own or control) and Scope 2 emissions (from purchased electricity and cooling), plus energy and water, with documented methods. The SLLP prefer three years of track record where feasible.
- Choose KPIs a lender will accept. Pick indicators material to your core business, with targets beyond business as usual and beyond regulatory minimums.
- Put controls around the data. Assign named owners, keep data lineage and add a review step, so the lender report and the external review draw on the same numbers.
- Line up reporting and review before signing. Agree the annual reporting format with the lender and appoint an external reviewer early, because target verification is mandatory under the SLLP.
Frequently Asked Questions
Get GCC Green-Finance Ready with Spectreco
Spectreco’s advisory team works alongside your finance, treasury and sustainability teams to set the baseline, choose lender-ready KPIs and organise the records your external reviewer will ask for.
The Virtual Sustainability Office combines that team with our ESG platform, so the same dataset serves your lender, regulator and investors every year, not only at signing.
Next step: book a Spectreco GCC green-finance readiness review through our Climate Finance & Green Capital advisory and see which GCC finance pools your company can qualify for today, and what data stands between you and the rest.

More From Our Blog

Your ESG Journey?