
Climate Risk for Omani Banks: CBO Expectations, Financed Emissions and PCAF Readiness

Climate Risk for Omani Banks: CBO, Financed Emissions and PCAF in 2026
Climate risk is now a supervisory expectation for every bank in Oman, not a voluntary ESG add-on. The Central Bank of Oman (CBO) has directed banks to disclose climate-related risks and practices from the 2026 financial year, and the Financial Services Authority (FSA) has set 1 January 2029 as the date IFRS S2 climate disclosure becomes mandatory for listed companies and financial institutions. The pillar most Omani banks have not yet built sits between those two dates: financed emissions, measured with the PCAF standard.
Spectreco, an ESG technology and advisory firm with offices in Atlanta, London, Lisbon, and Lahore, works with banks and financial institutions across all six GCC markets. This article sets out what the CBO expects on climate risk, what financed emissions are, how PCAF works, how these obligations connect to the 2029 IFRS S2 mandate, and the readiness path a bank should be on in 2026. For the wider listed-company view, see our Oman MSX ESG and ISSB reporting guide.
What Does the Central Bank of Oman Expect on Climate Risk?
The CBO expects every bank to disclose climate-related risks and practices from the 2026 financial year. Banks were directed to submit climate-risk implementation plans by June 2025, and the regulator is integrating climate risk into its financial stability oversight.
The direction started in 2023, when the CBO instructed all banks to prepare implementation plans for managing climate-related financial risk. Those plans were due by June 2025. From the 2026 financial year, disclosure of climate-related risks and practices becomes a supervisory expectation, a shift the CBO set out in its 2025 Financial Stability Report.
The CBO frames climate as a financial stability issue, not a reporting formality. Its concern is that climate shocks feed directly into credit, market, and operational risk on bank balance sheets.
Source: Oman Observer, Oman mandates banks to disclose climate-related risks from 2026.
Physical and Transition Risk in the Omani Context
The CBO has named both sides of the risk. On physical risk, it warned that Oman remains exposed to rising temperatures and extreme weather such as cyclones and flash floods, which threaten critical infrastructure, economic productivity, and the insurance sector. On transition risk, it flagged that Oman's hydrocarbon-reliant sectors face tightening international environmental regulation, carbon pricing, and shifting investor sentiment. For a bank, both translate into concentrated credit exposure.
Source: Oman Observer.
The Scenario-Analysis Gap
The CBO has been direct about the sector's weakest point: the absence of climate scenario analysis across the banking sector. In response, it has begun coordinating with national environmental bodies to support the classification of banks and borrowers by energy intensity. That classification is the first step toward the financed-emissions view the IFRS S2 metrics pillar will later require.
Source: Oman Observer.
The table below sets out the sequence of climate-risk and sustainability-disclosure milestones Omani banks face across both regulators.
What Are Financed Emissions?
Financed emissions are the greenhouse gas emissions linked to a bank's loans, bonds, and investments. They fall under Scope 3 Category 15 of the GHG Protocol and, for most banks, make up the large majority of the total carbon footprint.
A bank's own operations, its offices, branches, and data centres, produce Scope 1 and Scope 2 emissions. Those are small. The emissions that matter sit in the loan book and the investment portfolio, because a bank funds the activity of the companies it lends to and invests in.
The scale is not marginal. CDP found that the portfolio emissions of global financial institutions are on average over 700 times larger than their direct operational emissions. For most banks, financed emissions exceed 95% of the total footprint. Any climate-risk or IFRS S2 disclosure that ignores them is measuring the wrong thing.
Sources: CDP, The Time to Green Finance (2021); PCAF.
Do Omani Banks Use PCAF?
PCAF is the global standard for measuring financed emissions, and over 780 financial institutions have signed on worldwide. Omani banks are not yet required to use it, but it is the methodology IFRS S2 disclosure of Scope 3 Category 15 emissions relies on in practice.
PCAF (Partnership for Carbon Accounting Financials) is the global standard for measuring and disclosing the greenhouse gas emissions associated with loans and investments. Its Global GHG Accounting and Reporting Standard for the Financial Industry covers financed emissions, facilitated emissions, and insurance-associated emissions. More than 780 financial institutions are signatories.
PCAF gives banks a consistent way to attribute a borrower's emissions to a loan. The attribution factor is the bank's outstanding amount divided by the borrower's total equity and debt, so a bank counts only its share of a company's emissions. The standard covers asset classes including business loans, listed equity and corporate bonds, project finance, commercial real estate, mortgages, and motor vehicle loans.
Sources: PCAF; Persefoni, PCAF reporting guide.
The PCAF Data Quality Score
PCAF does not expect perfect data on day one. It scores each emissions figure on a quality scale from 1 to 5, where 1 is verified, reported data and 5 is the roughest estimate based on economic proxies. A bank can start disclosing at score 4 or 5 and improve the data over time. That matters for Omani banks starting now, because it removes the excuse of waiting for perfect counterparty data before beginning.
How the CBO Rules Connect to the FSA IFRS S2 Mandate
The CBO climate-risk expectation from 2026 is the near-term obligation. The FSA has adopted IFRS S1 and S2 with full application from 1 January 2029 and mandatory Scope 3 emissions from 1 January 2030, which is where financed emissions become a formal disclosure.
Two regulators shape the picture. The CBO supervises banks and now expects climate-risk disclosure from the 2026 financial year. The FSA governs listed-company and financial-institution reporting, and through Decision E/7/2026 it adopted IFRS S1 (General Requirements for Disclosure of Sustainability-related Financial Information) and IFRS S2 (Climate-related Disclosures), the ISSB standards issued in 2023.
The FSA timetable is phased. Full application of IFRS S1 and S2 begins on 1 January 2029, with the transition expected to start from the 2027 reporting cycle. Scope 3 greenhouse gas emissions, the category that holds financed emissions, become mandatory from 1 January 2030. Ahmed bin Ali al Mukhaini, who leads the FSA's Green and Sustainable Finance Team, framed the goal as improving the quality and usefulness of sustainability information for investment decisions, not simply the volume of disclosure.
For an MSX-listed bank, both regimes apply. The CBO expectation lands first, IFRS S2 follows, and the Scope 3 line brings financed emissions into audited reporting. Treating 2029 as distant is the trap: the governance, scenario analysis, and PCAF data behind IFRS S2 take years to build, not months.
Sources: Trowers & Hamlins, Oman adopts IFRS Sustainability Disclosure Standards (April 2026); Oman Observer, Oman moves towards mandatory sustainability disclosures for listed firms.
How Omani Banks Can Get PCAF and IFRS S2 Ready: A 5-Step Path
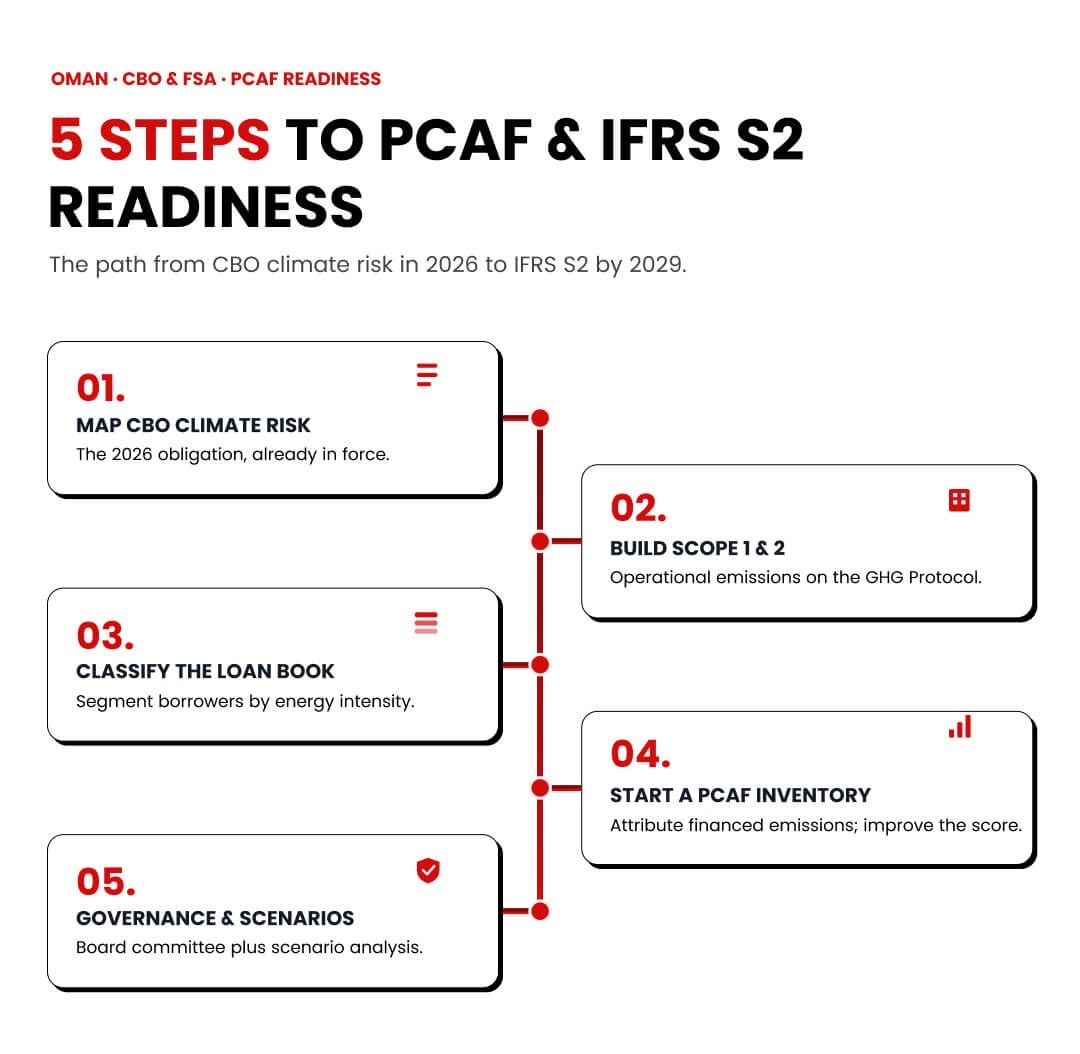
- Map the CBO climate-risk disclosure now. Confirm your 2026 climate-risk disclosure covers governance, the physical and transition risks the CBO named, and your current risk-management approach. This is the obligation already in force.
- Build a clean Scope 1 and Scope 2 inventory. Measure your own operational emissions across branches, offices, and data centres on the GHG Protocol. This is the smaller number, but it is the foundation auditors check first.
- Classify the loan book by energy intensity. Follow the CBO's own direction and segment borrowers by sector and energy intensity. This is the bridge between climate-risk classification and a financed-emissions inventory.
- Start a PCAF financed-emissions inventory. Pick the highest-exposure asset classes first, apply the PCAF attribution method, and disclose at whatever data quality score you can reach. Improve the score each cycle rather than waiting for perfect data.
- Stand up board governance and scenario analysis. Assign climate risk to a named board committee, document the mandate, and run the scenario analysis the CBO has flagged as missing. IFRS S2 requires all of it, and it cannot be retrofitted in the final year before 2029.
Frequently Asked Questions
Where Spectreco Fits
Omani banks face a sequence, not a single deadline: CBO climate-risk disclosure in 2026, then IFRS S2 by 2029, then Scope 3 financed emissions by 2030. The banks that absorb each step without disruption are the ones building the data and governance now, not in the final year.
Spectreco helps banks and financial institutions build that capability on one cloud-native ESG platform: a clean Scope 1 and 2 inventory, a PCAF financed-emissions model, board-level climate governance, and an IFRS S2 readiness plan. The same approach already supports banks elsewhere in the region, as in our guide to financed emissions for Pakistani banks under SECP IFRS S2.
To start, book a financed-emissions and climate-risk gap assessment with our team through Spectreco's Climate Finance & Green Capital advisory.
More From Our Blog
Your ESG Journey?